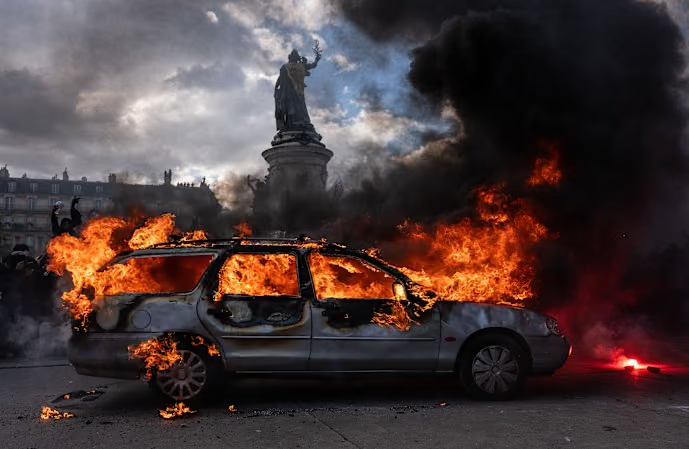
Paris is witnessing a dangerous intersection of politics and markets as France struggles to control rising borrowing costs while protests over education and the cost of living roil the capital.
Investors have been shunning French government bonds, pushing yields to their highest levels since 2002 and widening the spread with German 10‑year debt to its largest gap since 2011. That rise in yields makes servicing public debt more expensive just as politicians face intense pressure from voters.
At the centre of the risk is a feedback loop some researchers call a “doom loop”: political turmoil and market stress feed each other, limiting the authorities’ room to act and raising the cost of any fiscal concessions.
“The risk is less about a sudden debt default and more about a slow‑motion economic drag,”
wrote Michal Brzozowski and Joanna Siwinska‑Gorzelak, who have studied connections between populism and fiscal policy.
France’s public debt is now close to 120% of GDP, and the government forecasts it will pay more than €90 billion on interest next year, a bill that exceeds planned spending on defence and education and will crowd out other priorities.
That squeeze is playing out politically. President Emmanuel Macron leads a centrist administration without a legislative majority and is approaching the end of his term. His minority government is trying to pass a budget to narrow deficits, but looming presidential and likely legislative elections have hardened positions across the political spectrum.
Populist challengers on both the right and left are exploiting the uncertainty. Far‑right leader Marine Le Pen remains a top contender, while the far‑left Jean‑Luc Mélenchon has alarmed markets with proposals to effectively cancel parts of the nation’s debt. Economists say those plans lack credibility and would be difficult to enact if they ever reached power.
Observers warn the problem is not unique to France. Rising borrowing costs in other advanced economies, exacerbated by global geopolitical tensions that have lifted energy prices and revived inflation, are testing governments that have limited appetite for tax rises or spending cuts. “If you’re not going to solve it with new growth, and if interest payments are outrunning growth, then eventually what can’t go on forever won’t go on forever,” said Simon Radford of the Milken Institute.
Centrist parties are caught in a political Catch‑22, according to Ludovic Subran of Allianz: attempts to signal fiscal discipline can make voters see those parties as impotent, opening space for more extreme alternatives. That dynamic risks locking in a longer period of weak growth and tight public finances.
For households and key public services, the implications are tangible. Higher government interest bills mean less fiscal room to invest in schools, hospitals and infrastructure at a time when demonstrators are demanding better classrooms and more teachers. The protests that began with high school students have spread across parts of the country and added to the political frailty.
Looking ahead, markets are likely to remain sensitive to French political developments. Any large fiscal concession to calm the streets could further rattle investors and push yields higher, while austerity measures could inflame protests and boost support for populists. Policymakers in Paris face the difficult choice of trying to restore investor confidence without deepening domestic unrest, a balance that will shape France’s economy through the election cycle and beyond.